21 September 2026

Polarius Area Guide No. 01 — Living in St Julian's, Malta

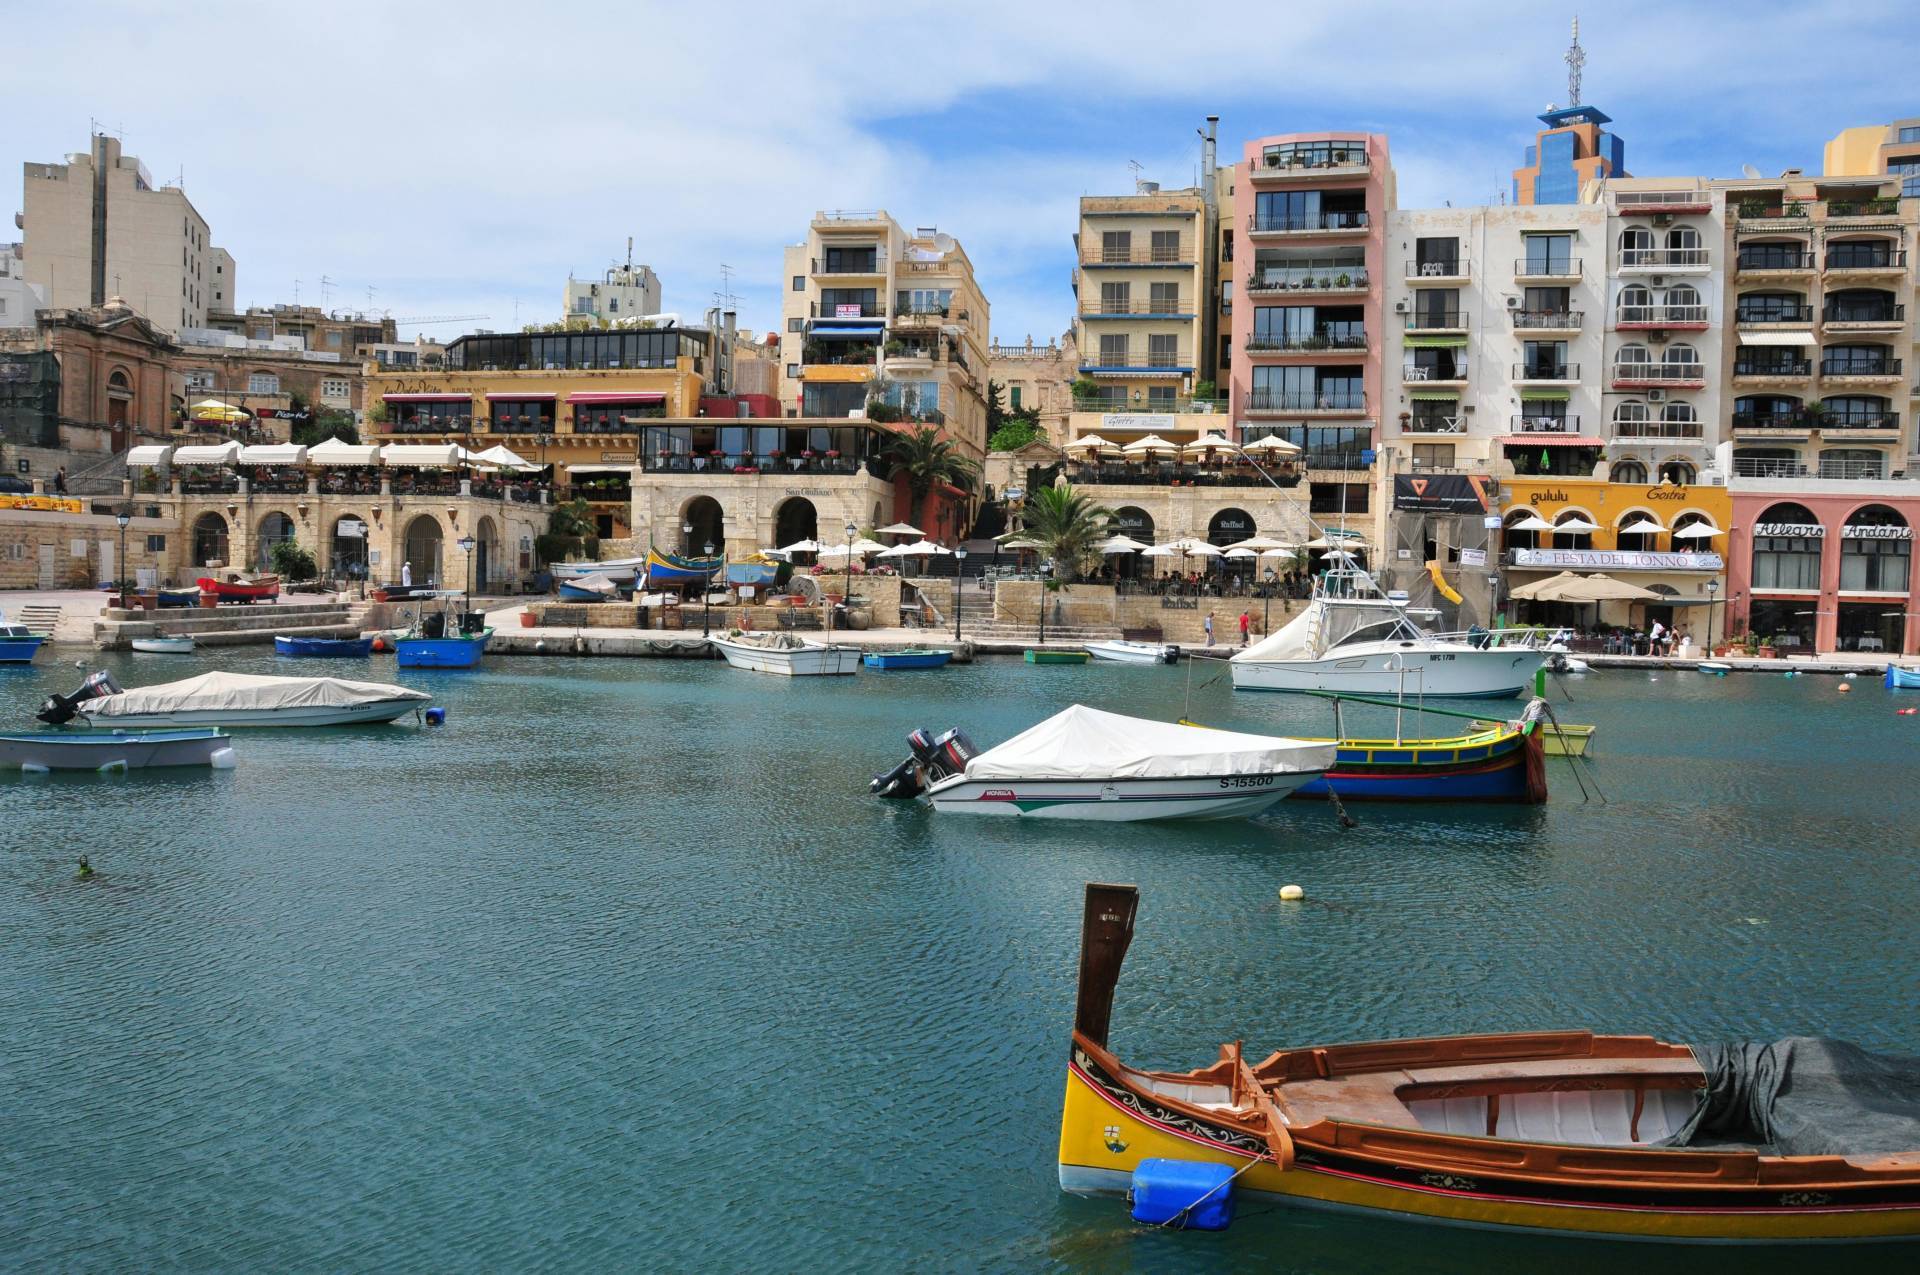
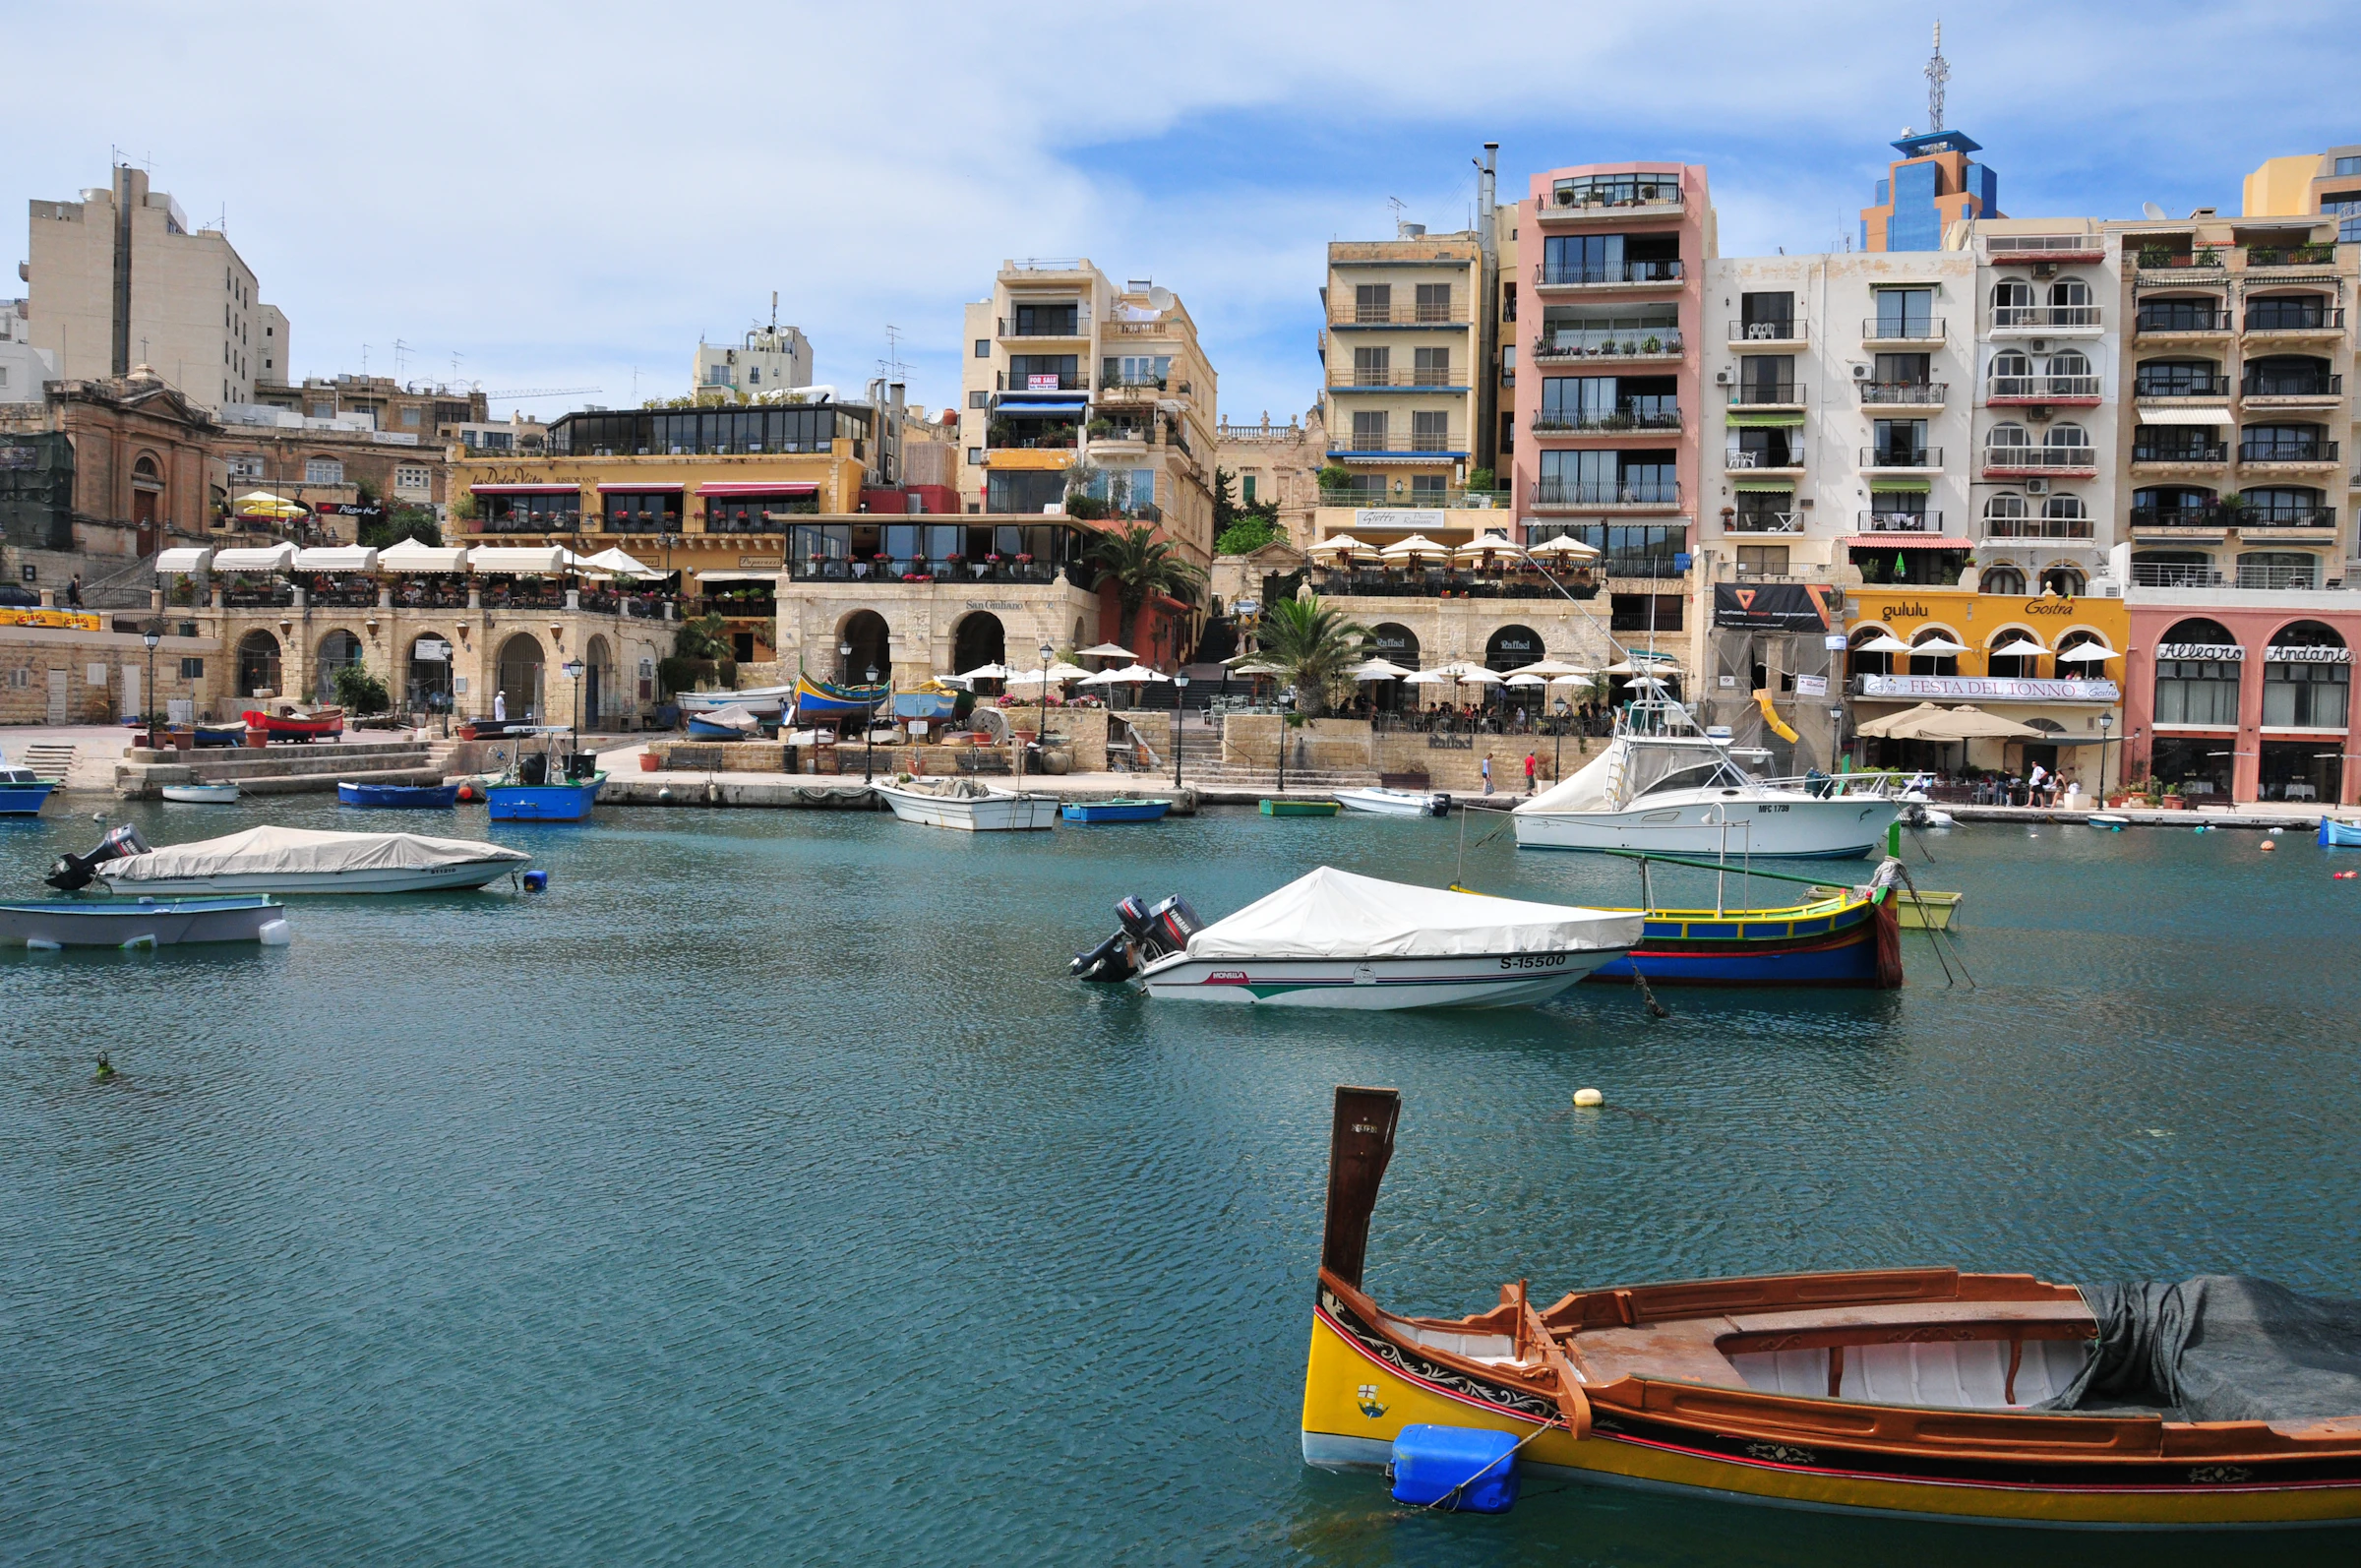
Spinola Bay waterfront and the St Julian's skyline, Malta

Polarius Area Guide · No. 01 · Published Fortnightly

Living in St Julian's, Malta

Photo: Cassidy Woods / Unsplash

€6,719Median Asking Price Per m²
St Julian's
+6.1%Malta House Price Index
Year On Year, Nominal
4.10%Gross Rental Yield
Malta Mainland, Q1 2026
58.6%Residents Who Are
Foreign Nationals

St Julian's is the most internationally owned square mile in the Maltese islands, and the numbers make the case more plainly than any brochure. Of the 14,709 people recorded as living in the town in July 2024, 8,614 — a little under 59 per cent — were foreign nationals, packed into 1.6 square kilometres at a density of some 9,200 residents per square kilometre. This is not a resort that empties in October. It is a working, year-round international community with a Michelin-starred restaurant, Malta's tallest building and two of the island's Special Designated Areas inside its boundaries.

For buyers, that combination produces an unusually legible market. Asking prices across St Julian's currently sit at a median of €6,719 per square metre, while Polarius stock in the district is priced at a blended €9,723 per square metre — a 45 per cent premium that is not a mispricing but a measure of the gap between the district's ageing secondary stock and its tower-and-marina prime tier. Understanding that gap is the whole exercise.

1
The district median understates the prime tier by roughly 45 per cent. St Julian's asks a median of €6,719 per square metre across all active listings. Our own six active listings blend to €9,723 per square metre, and the two tower addresses reach €13,113 and €15,112. Buyers comparing a headline median against a Mercury Tower or Ora East price are comparing two different markets that happen to share a postcode.
2
Two Special Designated Areas remove the permit question entirely. Both the Portomaso Development and the Pender Place and Mercury House site sit on Malta's SDA schedule, so EU and non-EU buyers alike may acquire one or more units there with no Acquisition of Immovable Property permit and no cap on the number of properties held. Outside an SDA, a non-resident buyer faces the permit process and minimum-value thresholds.
3
Volume, not just price, is carrying the Maltese market into 2026. Malta registered 13,339 residential transactions worth €3.97 billion in 2025, up 5.9 per cent by count and 12.5 per cent by value. April 2026 final deeds rose a further 9.4 per cent year on year. Price growth of 6.1 per cent nominal is being underwritten by genuine transactional depth rather than thin, high-headline trades.

District Overview & Lifestyle

St Julian's is best understood as five distinct places that share a name. Spinola Bay is the postcard — a horseshoe of painted luzzu fishing boats, seafront tables and the 1688 Spinola Palace behind them. Portomaso, immediately north, is the marina-and-tower quarter: a mixed-use waterfront development of hotels, apartments, restaurants and a tree-lined promenade wrapped around a private yacht basin, anchored by the 97.54-metre, 23-storey Portomaso Business Tower completed in 2001. Balluta Bay holds the district's Art Nouveau frontage and the Carmelite church. Paceville is the island's nightlife core, and the reason buyers should care which street they are on. Ta' Giorni and St Andrew's are the quieter residential slopes behind, where families and long-term residents actually live.

The skyline has changed decisively this cycle. Mercury Tower, designed by Zaha Hadid Architects and completed in 2023, rises 122 metres over 32 floors of residences and hotel space and is now Malta's tallest building; its three-level retail mall and public square opened in November 2023. That single project reset the district's price ceiling and pulled a branded-residence buyer profile into a market that had previously topped out with marina-front apartments.

Dining

St Julian's holds one MICHELIN Star, at Rosamì, which first earned the distinction in 2024 and retains it in the 2026 Malta guide. It is worth noting how concentrated Malta's fine dining has become: the 2026 guide lists seven starred restaurants island-wide, with two-starred ION Harbour, Noni and Under Grain in Valletta, De Mondion in Mdina, and Fernandõ Gastrotheque and Le GV next door in Sliema — every one of them inside a 25-minute drive of St Julian's. Below the starred tier, the Spinola Bay seafront and the Portomaso promenade carry the district's day-to-day restaurant trade.

Getting Around

Malta International Airport is about 10.5 kilometres away, under 25 minutes by car outside peak traffic. Malta Public Transport runs two dedicated Airport Direct coaches through the district — TD2 and TD3, every 30 minutes at €3 a passenger. Valletta and Sliema are reachable by bus or by the Sliema–Valletta ferry, and the district itself is comfortably walkable along the coast road from Balluta through Spinola to Portomaso.

The Vibe

Candidly: it depends on the street. A Portomaso or Ta' Giorni address is residential, international and quiet. A Paceville-adjacent address is not, and buyers should view any prospective purchase after dark as well as in daylight. The district's annual feast on the last Sunday of August — complete with the ġostra, a greased-pole scramble over the water — is a reminder that beneath the towers this remains a Maltese parish town with its own calendar.

Sales Market Analysis

Malta's national picture entering this cycle is one of steady, broadly based growth. The house price index rose 6.1 per cent year on year in nominal terms in the fourth quarter of 2025 and 3.61 per cent once inflation is stripped out, with quarterly growth of 1.3 per cent nominal, according to Global Property Guide. The more telling figure is volume: 13,339 residential transactions worth €3.97 billion across 2025, up 5.9 per cent by count and 12.5 per cent by value. Value outpacing count by more than six percentage points tells you the mix is shifting upmarket.

That momentum has continued into 2026. The National Statistics Office recorded 1,149 final deeds of sale worth €347.3 million in April 2026, a 9.4 per cent increase on April 2025, alongside 1,417 promise-of-sale agreements worth €530.3 million — up 6.1 per cent. Promise-of-sale agreements lead completions by several months, so a forward pipeline worth 53 per cent more than the deeds actually closing in the same month is a reasonable indication that the market is not about to stall.

The St Julian's Micro-Market

Against that national backdrop, St Julian's asks a median of €6,719 per square metre on live listings, placing it firmly in the island's upper tier but still below Valletta's €7,875 per square metre, per djar.ai's September 2026 locality data. The instructive exercise is to set that district median against our own active inventory.

BenchmarkPrice Per m²What It Represents
St Julian's median asking€6,719All live listings in the locality, including ageing secondary stock
Valletta median asking€7,875Malta's highest locality median — the national reference point
Polarius St Julian's blend€9,723Our six active listings, weighted by floor area
Marina and seafront tier€8,421–9,070Larger Portomaso and seafront apartments, 86–290 m²
Branded tower tier€13,113–15,112Mercury Tower and Ora East Tower — the district's ceiling

Two conclusions follow. First, the district median is a poor guide to prime pricing in St Julian's: the spread between the marina tier and the branded tower tier is roughly 1.8 times, and both sit above the locality median. Second, and counter-intuitively, floor area is currently cheaper than address. The 290-square-metre seafront apartment at €2.5 million works out at €8,621 per square metre, while a 53-square-metre residence in Mercury Tower commands €13,113. A buyer optimising for space per euro should be looking at the larger seafront and Portomaso floorplates; a buyer optimising for liquidity, brand and rental performance should be looking at the towers. These are genuinely different propositions.

Who Is Buying, And Why

The permit regime shapes demand more than any other single factor. Non-residents buying outside a Special Designated Area need an Acquisition of Immovable Property permit and must meet minimum-value thresholds — €107,670 for an apartment or maisonette, €179,400 for other property — and may hold only that one property. Inside an SDA, those restrictions fall away completely: EU and non-EU buyers may acquire one or more units with no permit at all. St Julian's contains two such zones, the Portomaso Development and the Pender Place and Mercury House site, which is precisely why international capital concentrates in them.

On the income side, Malta mainland gross rental yields averaged 4.10 per cent in the first quarter of 2026. St Julian's and neighbouring Sliema sit at the top of the national rental market, with one-bedroom apartments achieving €1,100–1,500 a month and two-bedroom units €1,500–2,200, against national averages of €900 and €1,200 respectively — at the midpoint of each band, some 44 and 54 per cent above the corresponding national figure. Demand here is year-round rather than seasonal, underpinned by the resident international workforce described above, which is what gives St Julian's lettings their occupancy strength. The prime end of the district is nonetheless bought principally for what it is rather than for what it earns: a scarce, permit-free, internationally liquid asset in a market with genuine transactional depth. Income is a useful component of the return; the case rests on the asset.

Strategic Verdict

St Julian's offers something rare in the Mediterranean: a genuinely year-round international community, a legally frictionless route to ownership inside two Special Designated Areas, and a national market whose 6.1 per cent nominal price growth is underwritten by rising transaction volumes rather than scarcity alone.

Our reading of the current pricing is that the larger seafront and Portomaso floorplates are the better value on a per-square-metre basis, at €8,421–9,070 against €13,113 and above in the branded towers. The towers earn their premium in liquidity, letting performance and resale narrative, not in space. Buyers should decide which of those two things they are actually purchasing before comparing prices — and should treat the €6,719 district median as a floor reference, not a valuation.

The caution is specific rather than general: proximity to Paceville materially affects both amenity and resale profile, and it is not visible in a floor plan. View after dark.

Featured Local Properties

Six active Polarius listings in St Julian's, spanning the district's full range from a one-bedroom residence in Malta's tallest building to a 290-square-metre seafront apartment.

€2,500,000
Seafront four-bedroom apartment for sale in St Julian's, Malta
Seafront Residence
St Julian's
4 Bed | 5 Bath | 290 m²

Largest Floorplate In Our St Julian's Stock

The district's space play at €8,621 per square metre — well below the branded tower tier despite a direct seafront position.

Ref 86279571
€1,600,000
Penthouse for sale in Portomaso, St Julian's, Malta
Portomaso Penthouse
St Julian's
2 Bed | 3 Bath | 190 m²

Special Designated Area — No AIP Permit

Inside the Portomaso SDA, so open to EU and non-EU buyers with no permit and no cap on units held.

Ref 86046136
€1,490,000
Two-bedroom apartment for sale in Ora East Tower, St Julian's, Malta
Ora East Tower
St Julian's
2 Bed | 2 Bath | 98.6 m²

Highest Rate Per m² In The District

At €15,112 per square metre, this sets the current ceiling for St Julian's tower stock.

Ref 86101596
€780,000
Two-bedroom seaview apartment for sale in St Julian's, Malta
Seaview Apartment
St Julian's
2 Bed | 2 Bath | 86 m²

Mid-Market Entry With Sea Frontage

€9,070 per square metre — close to our portfolio blend, with a two-bedroom letting band of €1,500–2,200 a month.

Ref 87029571
€695,000
South-facing one-bedroom residence on the 13th floor of Mercury Tower, St Julian's, Malta
Mercury Tower
13th Floor
1 Bed | 1 Bath | 53 m²

Zaha Hadid Architects — Malta's Tallest Building

South-facing, in the 122-metre tower completed in 2023, and inside the Pender Place and Mercury House SDA.

Ref 85986327
€650,000
One-bedroom seaview apartment for sale in St Julian's, Malta
Seaview Apartment
St Julian's
1 Bed | 1 Bath | 75.9 m²

Most Space Per Euro In Our St Julian's Stock

€8,564 per square metre and 75.9 m² — a one-bedroom with genuinely unusual proportions for the district.

Ref 87030418
Read Our Complete Guide To Buying Property In Malta AIP permits, Special Designated Areas, stamp duty and the MPRP residency route
→
Browse Every Polarius Home In Malta St Julian's, Sliema, Portomaso and the wider island
→
Contact Us Today

Considering St Julian's?

Whether you are weighing a Special Designated Area purchase, comparing the marina tier against the branded towers, or simply want an honest view on which streets to avoid, we would be glad to talk it through.

Polarius Area Guide — No. 01 · Published 21 September 2026
A New District, Every Fortnight
Lee Michael Horan · International Luxury Real Estate · Polarius International Real Estate
Market data is indicative and sourced as listed above. This article is editorial commentary and does not constitute investment, tax or legal advice.
Back

The latest press articles

  • A prospective buyer reviewing Bali property and PT PMA registration plans from home

    Bali Freehold Changes 2026, Part II: Inside the PT PMA and KBLI Registration Squeeze

    Ask five people in Bali what happened to foreign property investment in June 2026, and you will likely get five different answers — a freehold ban, a PT PMA shutdown, a licensing overhaul, or nothing much at all. The confusion is understandable. Three genuinely separate regulatory threads landed within a few months of each other: a provincial crackdown on nominee ownership in February, a closure of new company registration in a defined list of business categories from around May, and a routine national reclassification of business codes with an administrative deadline in June. Only one of those three is actually new and restrictive. The other two are being widely misdescribed.

    This matters because the practical question for a foreign buyer — or a foreign owner already holding property through a PT PMA — is not "is freehold banned." It never was available in the first place, as Part I sets out. The real question is narrower and more useful: can a new PT PMA still be registered to buy Bali property today, in which business categories, at what scale, and what happens to a company that was set up before any of this started.

    Below, we work through what closed, what is merely being reorganised, what the workarounds being used in practice actually look like, and — a question we are increasingly asked directly — what it means if you already hold a Bali property through a PT PMA and want to sell it on.

    Read more
  • Rice terraces in Bali, Indonesia, the agricultural land at the centre of the 2026 property regulations

    Bali Freehold Changes 2026: What Foreign Buyers Need to Know

    For years, the phrase "freehold in Bali" has done a lot of quiet work in property conversations — used loosely by agents, buyers and even some notaries to describe land that, on paper, sits in someone else's name. It was never quite true, but it was rarely tested.

    In February 2026, it was tested. A new Bali provincial regulation put criminal penalties behind rules that had existed on paper since 1960, and closed off an arrangement thousands of foreign owners had relied on. For much of the year, agents, notaries and lawyers across the island gave different answers to the same question: can a foreigner still buy freehold in Bali?

    Below, we set out what actually changed, what it means if you already own, and the routes that remain genuinely open to foreign buyers in the second half of 2026.

    Read more
  • Hôtel Ritz Paris, Place Vendôme — emblematic of European trophy hospitality assets driving institutional investment in 2026

    The Off-Market Shift: European Luxury Hotel Investment in 2026

    For much of the post-pandemic cycle, European hotel investment has been characterised by openly marketed processes — published teasers, structured information memoranda, broker-led auctions. That model is now being quietly displaced at the upper end of the market. The largest trophy transactions of 2026 are moving under exclusivity, intermediated through closed networks, and concluding with a single qualified buyer.

    For institutional capital, family offices and sovereign vehicles, the question is no longer whether the right opportunities exist in European luxury hospitality. It is how to access them.

    Read more
  • Aerial view of a stepped, terraced Manchester development with glass-fronted floors, landscaped rooftop terraces and outdoor dining, overlooking the city skyline

    Manchesterism: Andy Burnham's Manchester Property Blueprint. Can It Work Elsewhere?

    Britain's new Prime Minister spent nine years running Greater Manchester before he ran the country — and the property market he leaves behind tells you what his regeneration playbook actually looks like in practice. Here's what Andy Burnham built, why it worked, and whether it can be repeated elsewhere in the UK.

    Read more
  • Luxury villa with private pool and sea views on the French Riviera — renting vs buying on the Côte d'Azur, Polarius Market Insights 2026

    Renting vs Buying on the French Riviera: The Summer Calculation

    Every summer on the Côte d'Azur ends the same way for a certain kind of renter: with the question of what it would actually cost to own. This analysis sets out the full financial picture — acquisition costs, annual running costs, the French notary fee structure, and the break-even point at which buying a property on the French Riviera becomes the sharper decision. If you are spending €80,000 or more per year on Riviera rentals, the numbers here are for you.

    Read more
  • Chateau du Cap exceptional luxury residential estate for sale in Cap d'Antibes France

    What Is a Family Office? Inside the Private Wealth Real Estate Shift

    Family offices control trillions in private wealth globally—and real estate sits at the absolute heart of how they deploy it. 

    While traditional buyers rely on public listings, these ultra-high-net-worth structures operate with institutional discipline and an uncompromising preference for off-market access. 

    For anyone navigating the upper echelons of the luxury property market, understanding how family offices are quietly rewriting the rules of acquisition is no longer optional.

    Read more
  • Aerial view of a private luxury villa with an infinity pool overlooking the Pampelonne coastline near Saint-Tropez, surrounded by pine trees and Mediterranean scrubland, on a clear summer day.

    Saint-Tropez Villa Rentals 2026: Prices, Availability & Insider Guide

    Saint-Tropez in summer 2026 is a landlord’s market - and it has been for some time.

    Peak-week villa rates have climbed 12–18% since 2024, the best properties are booked nearly a year in advance, and a growing share of trophy lets never appear on any public platform.

    For those still planning a French Riviera summer, the window is narrow but not closed. This guide covers where prices stand, which zones still offer availability, and what the most experienced renters do to secure exceptional properties when the obvious options are gone.

    Read more
  • Two luxury sports cars on a waterfront street in Monte Carlo, with upscale shops, high-rise buildings, and green hills in the background.

    Dubai vs Monaco - Where Billionaires Buy in 2026

    Two zero-tax jurisdictions. Two fundamentally different investment theses. In 2026, the choice between Dubai and Monaco has become more nuanced — and more consequential — than at any point in the past decade. Polarius analyses both markets in depth.

    Read more
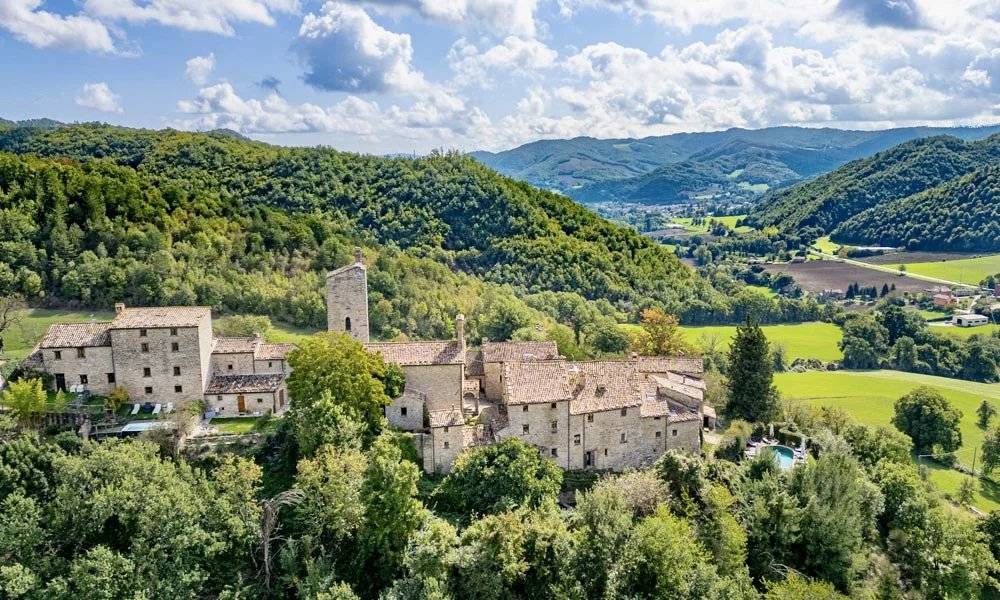
  • Rolling hills and stone estate in Le Marche, Italy — luxury property market insight | Polarius Real Estate

    Le Marche: The Last Undervalued Luxury Market in Italy

    While Tuscany and the Amalfi Coast have long captured the imagination of international buyers, a quieter story has been unfolding further up Italy's Adriatic coast.

    Le Marche - five provinces of medieval hilltowns, pristine coastline and UNESCO heritage - offers everything its more famous neighbours do, at prices that remain, by any European luxury standard, startlingly undervalued.

    In 2026, with Italy's flat tax regime now attracting serious ultra-high-net-worth attention and national property prices rising at their fastest rate in a decade, the window for early-mover advantage is narrowing. This is the case for Le Marche.

    Read more
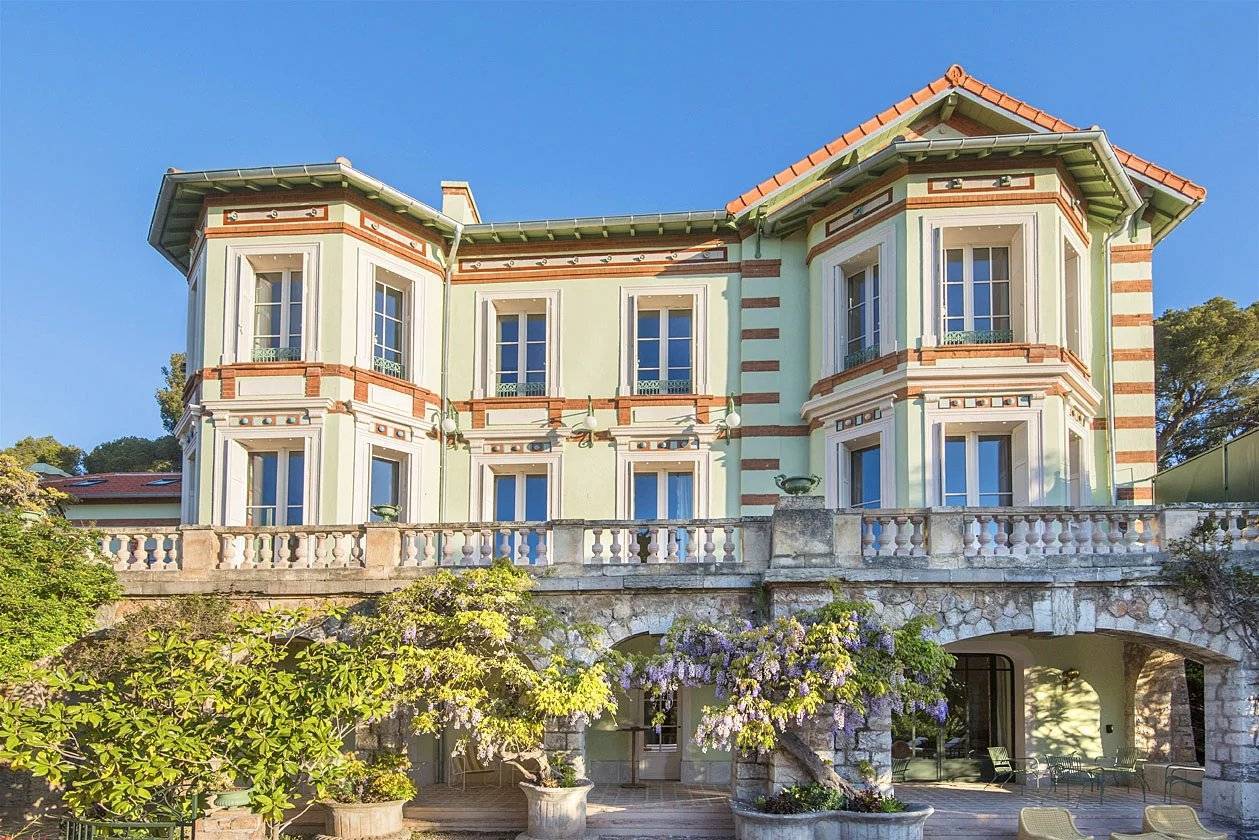
  • Belle Époque luxury villa overlooking the Mediterranean in Hyères on the French Riviera

    Why Hyères Is Quietly Becoming the French Riviera’s Next Luxury Escape

    For decades, the narrative of Riviera luxury has revolved around the same names: Saint-Tropez, Cannes, Cap-Ferrat and Monaco. Yet a subtle shift is beginning to emerge among high-net-worth travellers and second-home buyers searching for something increasingly rare on the Côte d’Azur: privacy, authenticity and space.

    That shift is bringing new attention to Hyères.

    Long appreciated by sailors, artists, nature lovers and discerning French families, Hyères has historically remained outside the international luxury spotlight that transformed other Riviera destinations into global status symbols. Today, however, changing travel behaviour and evolving definitions of luxury are positioning this Mediterranean town as one of the most interesting emerging lifestyle destinations in Southern Europe.

    Read more

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.