St Julian's is the most internationally owned square mile in the Maltese islands, and the numbers make the case more plainly than any brochure. Of the 14,709 people recorded as living in the town in July 2024, 8,614 — a little under 59 per cent — were foreign nationals, packed into 1.6 square kilometres at a density of some 9,200 residents per square kilometre. This is not a resort that empties in October. It is a working, year-round international community with a Michelin-starred restaurant, Malta's tallest building and two of the island's Special Designated Areas inside its boundaries.
For buyers, that combination produces an unusually legible market. Asking prices across St Julian's currently sit at a median of €6,719 per square metre, while Polarius stock in the district is priced at a blended €9,723 per square metre — a 45 per cent premium that is not a mispricing but a measure of the gap between the district's ageing secondary stock and its tower-and-marina prime tier. Understanding that gap is the whole exercise.
District Overview & Lifestyle
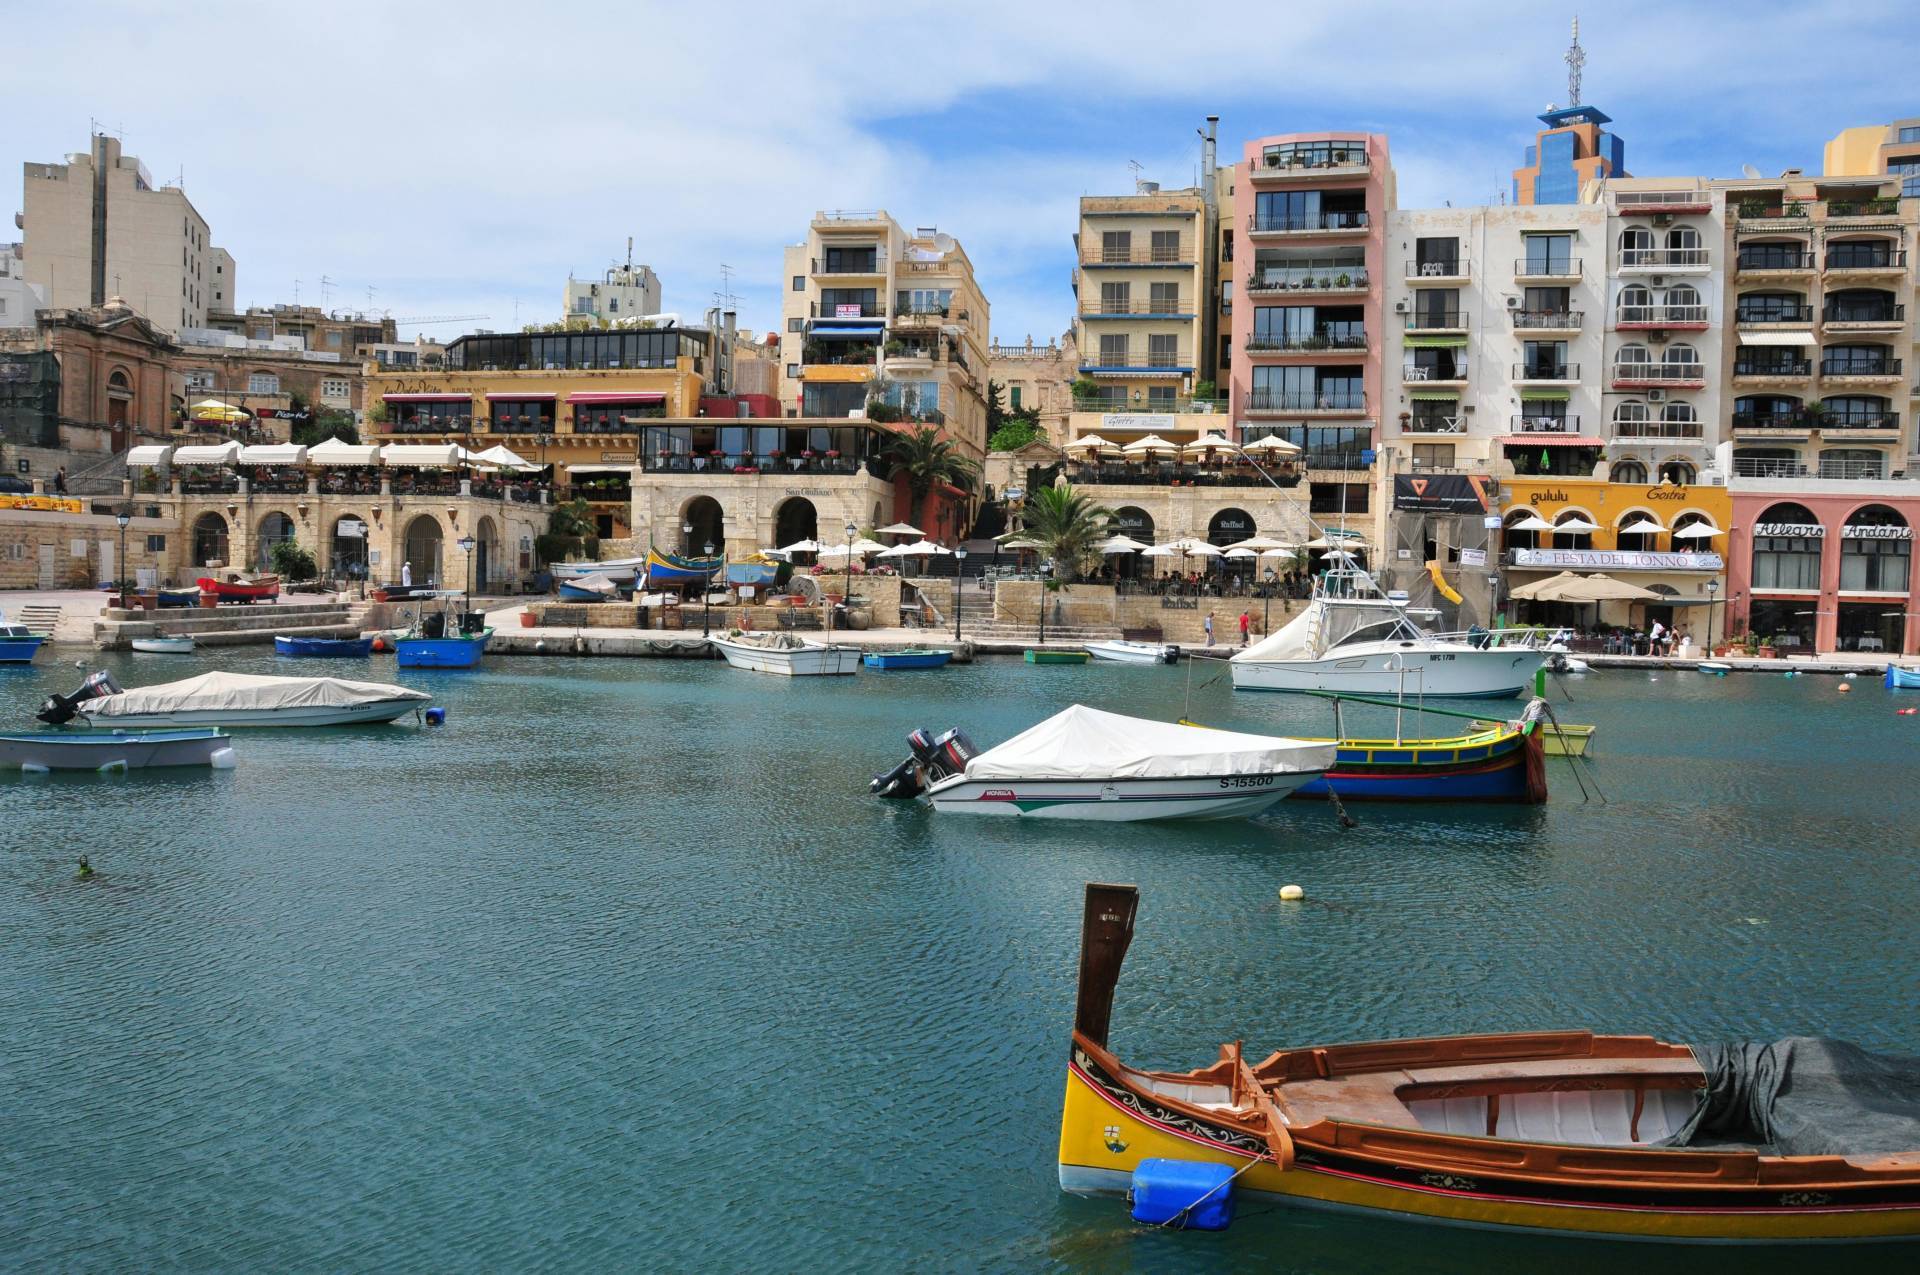
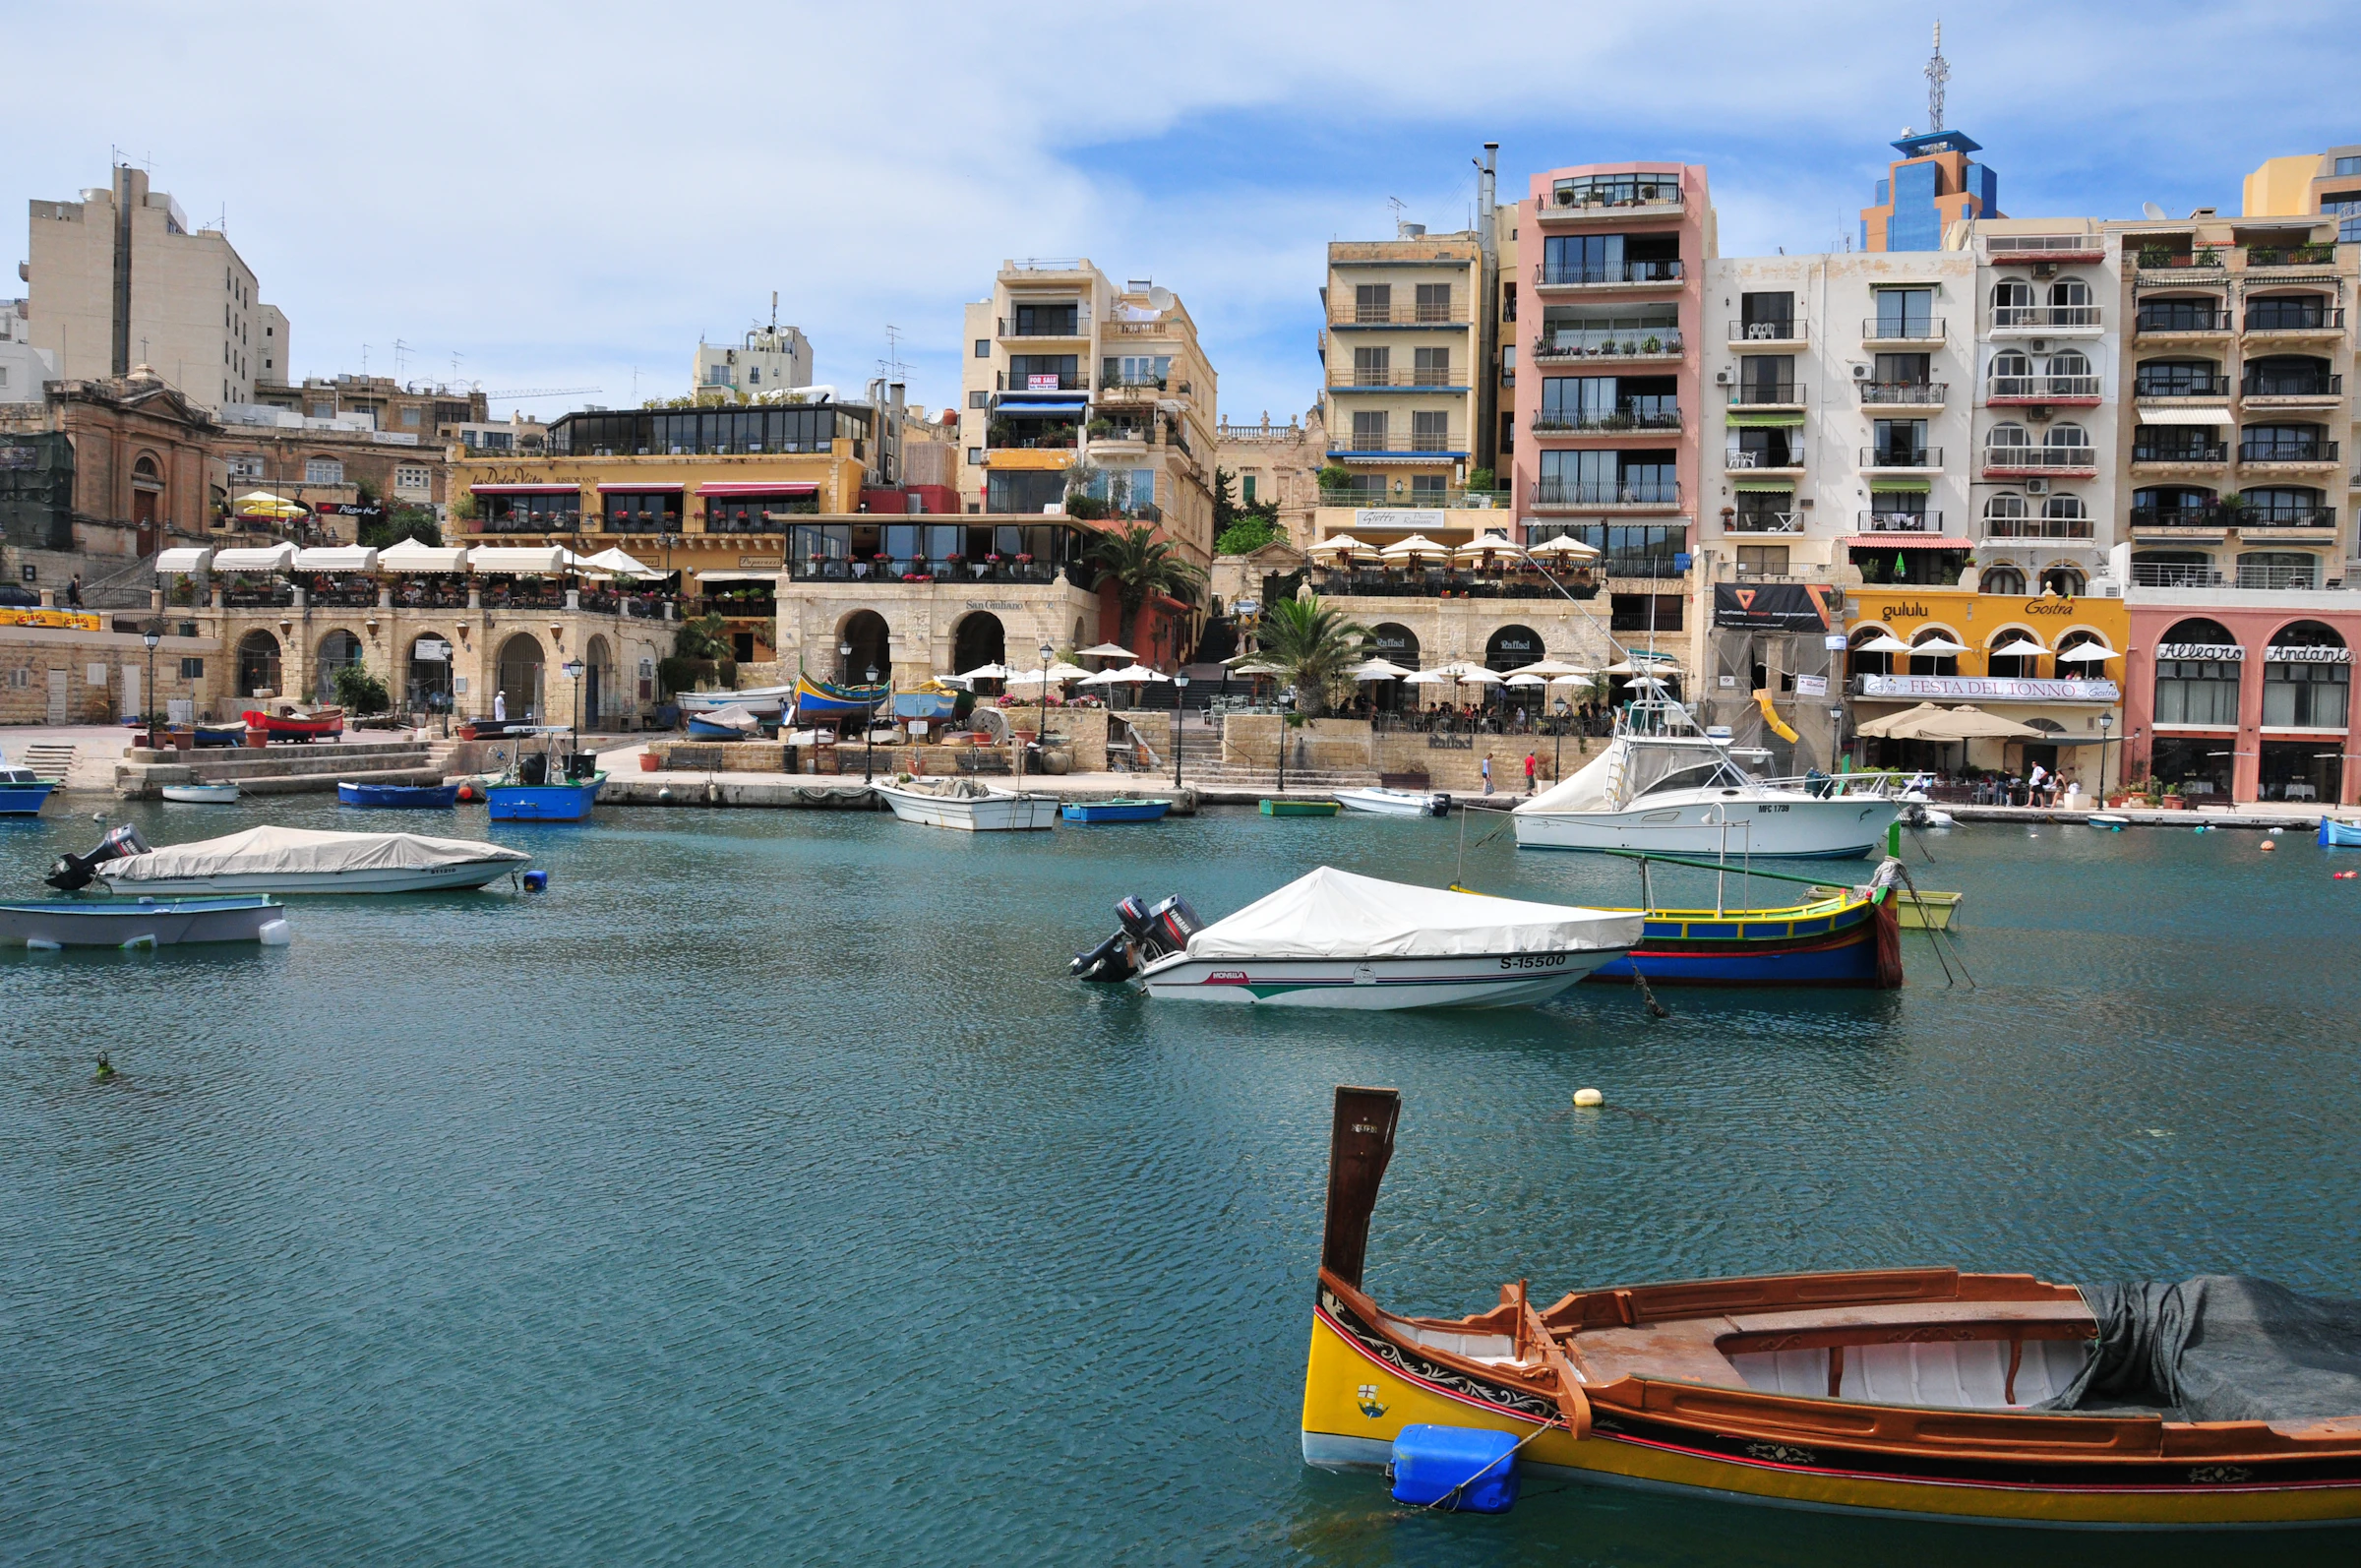
St Julian's is best understood as five distinct places that share a name. Spinola Bay is the postcard — a horseshoe of painted luzzu fishing boats, seafront tables and the 1688 Spinola Palace behind them. Portomaso, immediately north, is the marina-and-tower quarter: a mixed-use waterfront development of hotels, apartments, restaurants and a tree-lined promenade wrapped around a private yacht basin, anchored by the 97.54-metre, 23-storey Portomaso Business Tower completed in 2001. Balluta Bay holds the district's Art Nouveau frontage and the Carmelite church. Paceville is the island's nightlife core, and the reason buyers should care which street they are on. Ta' Giorni and St Andrew's are the quieter residential slopes behind, where families and long-term residents actually live.
The skyline has changed decisively this cycle. Mercury Tower, designed by Zaha Hadid Architects and completed in 2023, rises 122 metres over 32 floors of residences and hotel space and is now Malta's tallest building; its three-level retail mall and public square opened in November 2023. That single project reset the district's price ceiling and pulled a branded-residence buyer profile into a market that had previously topped out with marina-front apartments.
Dining
St Julian's holds one MICHELIN Star, at Rosamì, which first earned the distinction in 2024 and retains it in the 2026 Malta guide. It is worth noting how concentrated Malta's fine dining has become: the 2026 guide lists seven starred restaurants island-wide, with two-starred ION Harbour, Noni and Under Grain in Valletta, De Mondion in Mdina, and Fernandõ Gastrotheque and Le GV next door in Sliema — every one of them inside a 25-minute drive of St Julian's. Below the starred tier, the Spinola Bay seafront and the Portomaso promenade carry the district's day-to-day restaurant trade.
Getting Around
Malta International Airport is about 10.5 kilometres away, under 25 minutes by car outside peak traffic. Malta Public Transport runs two dedicated Airport Direct coaches through the district — TD2 and TD3, every 30 minutes at €3 a passenger. Valletta and Sliema are reachable by bus or by the Sliema–Valletta ferry, and the district itself is comfortably walkable along the coast road from Balluta through Spinola to Portomaso.
The Vibe
Candidly: it depends on the street. A Portomaso or Ta' Giorni address is residential, international and quiet. A Paceville-adjacent address is not, and buyers should view any prospective purchase after dark as well as in daylight. The district's annual feast on the last Sunday of August — complete with the ġostra, a greased-pole scramble over the water — is a reminder that beneath the towers this remains a Maltese parish town with its own calendar.
Sales Market Analysis
Malta's national picture entering this cycle is one of steady, broadly based growth. The house price index rose 6.1 per cent year on year in nominal terms in the fourth quarter of 2025 and 3.61 per cent once inflation is stripped out, with quarterly growth of 1.3 per cent nominal, according to Global Property Guide. The more telling figure is volume: 13,339 residential transactions worth €3.97 billion across 2025, up 5.9 per cent by count and 12.5 per cent by value. Value outpacing count by more than six percentage points tells you the mix is shifting upmarket.
That momentum has continued into 2026. The National Statistics Office recorded 1,149 final deeds of sale worth €347.3 million in April 2026, a 9.4 per cent increase on April 2025, alongside 1,417 promise-of-sale agreements worth €530.3 million — up 6.1 per cent. Promise-of-sale agreements lead completions by several months, so a forward pipeline worth 53 per cent more than the deeds actually closing in the same month is a reasonable indication that the market is not about to stall.
The St Julian's Micro-Market
Against that national backdrop, St Julian's asks a median of €6,719 per square metre on live listings, placing it firmly in the island's upper tier but still below Valletta's €7,875 per square metre, per djar.ai's September 2026 locality data. The instructive exercise is to set that district median against our own active inventory.
| Benchmark | Price Per m² | What It Represents |
|---|---|---|
| St Julian's median asking | €6,719 | All live listings in the locality, including ageing secondary stock |
| Valletta median asking | €7,875 | Malta's highest locality median — the national reference point |
| Polarius St Julian's blend | €9,723 | Our six active listings, weighted by floor area |
| Marina and seafront tier | €8,421–9,070 | Larger Portomaso and seafront apartments, 86–290 m² |
| Branded tower tier | €13,113–15,112 | Mercury Tower and Ora East Tower — the district's ceiling |
Two conclusions follow. First, the district median is a poor guide to prime pricing in St Julian's: the spread between the marina tier and the branded tower tier is roughly 1.8 times, and both sit above the locality median. Second, and counter-intuitively, floor area is currently cheaper than address. The 290-square-metre seafront apartment at €2.5 million works out at €8,621 per square metre, while a 53-square-metre residence in Mercury Tower commands €13,113. A buyer optimising for space per euro should be looking at the larger seafront and Portomaso floorplates; a buyer optimising for liquidity, brand and rental performance should be looking at the towers. These are genuinely different propositions.
Who Is Buying, And Why
The permit regime shapes demand more than any other single factor. Non-residents buying outside a Special Designated Area need an Acquisition of Immovable Property permit and must meet minimum-value thresholds — €107,670 for an apartment or maisonette, €179,400 for other property — and may hold only that one property. Inside an SDA, those restrictions fall away completely: EU and non-EU buyers may acquire one or more units with no permit at all. St Julian's contains two such zones, the Portomaso Development and the Pender Place and Mercury House site, which is precisely why international capital concentrates in them.
On the income side, Malta mainland gross rental yields averaged 4.10 per cent in the first quarter of 2026. St Julian's and neighbouring Sliema sit at the top of the national rental market, with one-bedroom apartments achieving €1,100–1,500 a month and two-bedroom units €1,500–2,200, against national averages of €900 and €1,200 respectively — at the midpoint of each band, some 44 and 54 per cent above the corresponding national figure. Demand here is year-round rather than seasonal, underpinned by the resident international workforce described above, which is what gives St Julian's lettings their occupancy strength. The prime end of the district is nonetheless bought principally for what it is rather than for what it earns: a scarce, permit-free, internationally liquid asset in a market with genuine transactional depth. Income is a useful component of the return; the case rests on the asset.
Strategic Verdict
St Julian's offers something rare in the Mediterranean: a genuinely year-round international community, a legally frictionless route to ownership inside two Special Designated Areas, and a national market whose 6.1 per cent nominal price growth is underwritten by rising transaction volumes rather than scarcity alone.
Our reading of the current pricing is that the larger seafront and Portomaso floorplates are the better value on a per-square-metre basis, at €8,421–9,070 against €13,113 and above in the branded towers. The towers earn their premium in liquidity, letting performance and resale narrative, not in space. Buyers should decide which of those two things they are actually purchasing before comparing prices — and should treat the €6,719 district median as a floor reference, not a valuation.
The caution is specific rather than general: proximity to Paceville materially affects both amenity and resale profile, and it is not visible in a floor plan. View after dark.
Featured Local Properties
Six active Polarius listings in St Julian's, spanning the district's full range from a one-bedroom residence in Malta's tallest building to a 290-square-metre seafront apartment.

St Julian's
Largest Floorplate In Our St Julian's Stock
The district's space play at €8,621 per square metre — well below the branded tower tier despite a direct seafront position.
View Property →
St Julian's
Special Designated Area — No AIP Permit
Inside the Portomaso SDA, so open to EU and non-EU buyers with no permit and no cap on units held.
View Property →
St Julian's
Highest Rate Per m² In The District
At €15,112 per square metre, this sets the current ceiling for St Julian's tower stock.
View Property →
St Julian's
Mid-Market Entry With Sea Frontage
€9,070 per square metre — close to our portfolio blend, with a two-bedroom letting band of €1,500–2,200 a month.
View Property →
13th Floor
Zaha Hadid Architects — Malta's Tallest Building
South-facing, in the 122-metre tower completed in 2023, and inside the Pender Place and Mercury House SDA.
View Property →
St Julian's
Most Space Per Euro In Our St Julian's Stock
€8,564 per square metre and 75.9 m² — a one-bedroom with genuinely unusual proportions for the district.
View Property →